

The Daily Meaning
Take your mornings to the next level with a daily dose of perspective and encouragement to start your day off right. Sign-up for a free, short-form blog delivered to your inbox each morning, 7 days per week. Some days we talk about money, but usually not. We believe you’ll take away something valuable to help you on your journey. Sign up to join the hundreds of people who read Travis’s blog each morning.
Archive
- October 2026
- September 2026
- August 2026
- July 2026
- June 2026
- May 2026
- April 2026
- March 2026
- February 2026
- January 2026
- December 2025
- November 2025
- October 2025
- September 2025
- August 2025
- July 2025
- June 2025
- May 2025
- April 2025
- March 2025
- February 2025
- January 2025
- December 2024
- November 2024
- October 2024
- September 2024
- August 2024
- July 2024
- June 2024
- May 2024
- April 2024
- March 2024
- February 2024
- January 2024
- December 2023
- November 2023
- October 2023
- September 2023
- August 2023
- July 2023
- June 2023
- May 2023
- April 2023
- March 2023
- February 2023
- January 2023
- December 2022
- November 2022
- August 2021
- November 2020
- July 2020
- June 2020
- April 2020
- March 2020
- February 2020
- October 2019
- September 2019
70,000 Steps vs. 1 Excuse
Something powerful happens to us when we remove excuses. If we take the excuses off the table and tell ourselves that there is no other way but through it, it's amazing what we can accomplish.
A few days ago, I wrote about rules and exceptions. Specifically, the need for each of us to establish clear, firm rules in our lives, while also defining the exceptions. Exceptions aren't a bad thing, but not everything can be an exception. So we need to give ourselves permission to make exceptions to the rules that don't let us spiral.
Today, I want to lean harder into the rules. In the absence of the narrow, specifically named exceptions, we need to let our rules be our rules... no excuses. Something amazing happens when we get rid of the excuses. If there are no excuses and the exceptions don't apply, we have no choice but to attack it head-on. This blog is one such example. I've had so many excuses over these past four years: sickness, travel, overwhelm, relational stress, work stress, parental stress, tragedy, and injury. There are so many nights I just want an excuse! However, excuses aren't allowed, and in this arena of my life, there are no exceptions. If 1,000 people are waiting to receive an e-mail, the work must be done. The product of this? 1,400+ consecutive days of writing, editing, and publishing an article. That's the power of no excuses. It turns the unfathomable into reality.
I had a similar experience this week, but with my steps. As I've mentioned in the past, I started a new habit in January 2025: I try to get 12,000+ steps each day, but I make sure I average at least 10,000 daily steps each month. 20 months in, my record is flawless.....until September 2026. After travel, sickness, too much desk time, and some back pain, I found myself woefully short of my 10,000 average toward the end of the month. After crunching the numbers, I realized I needed to get 69,000 steps in the final four days of the month to hit my 10,000/day goal.
No excuses! I didn't necessarily have excess time for this, and I didn't feel particularly well, but a commitment is a commitment. Over the last four days of the month, I ripped out 26,000, 10,000, 18,000, and 16,000 steps.....70,000 in total. I hated doing it, but there are no excuses.
Something powerful happens to us when we remove excuses. If we take the excuses off the table and tell ourselves that there is no other way but through it, it's amazing what we can accomplish. Whatever you're trying to accomplish, whether career, finance, or some other endeavor, just get rid of the excuses. Do what needs to be done, force yourself to go through it, and see what happens. You'll likely end up pleasantly surprised. There's always more in you than you know.
____
Did someone forward you this post? We're glad you're here! If you'd like to subscribe to The Daily Meaning to receive these posts directly in your inbox (for free!), just CLICK THIS LINK. It only takes 10 seconds.
Sunk Costs: QB Edition
Social media was abuzz yesterday after news that Vikings quarterback J.J. McCarthy was traded to the New York Giants. Some loved it, some hated it, and some were flat-out confused. The most prevalent narrative I heard, though, was this: Why would the Vikings trade a 10th overall pick (the spot McCarthy was originally selected) for a 5th-round draft pick?
Social media was abuzz yesterday after news that Vikings quarterback J.J. McCarthy was traded to the New York Giants. Some loved it, some hated it, and some were flat-out confused. The most prevalent narrative I heard, though, was this: Why would the Vikings trade a 10th overall pick (the spot McCarthy was originally selected) for a 5th-round draft pick?
Yes, it's true that McCarthy was selected as one of the top 10 players in his draft. Yes, it's true that the Vikings received a 5th-round draft pick in return. Yes, it's true that a top-10 draft pick is much more valuable than a 5th-round draft pick. Unfortunately, none of that matters.
The Vikings didn't trade a draft pick. They traded a player they selected with said draft pick. Once they selected him, it doesn't matter where they selected him. All that matters is how much value he does or doesn't have. And yesterday, the Vikings decided his value was approximately that of a future 5th-round draft pick. That's called a sunk cost. The moment the Vikings picked him, it didn't matter what it cost them. They'd already paid the cost, and now all they had was whatever value the QB market attributed to him.
This same principle applies to everything in our lives. That car sitting in your garage? It doesn't matter what you paid for it. It's worth what it's worth....which is probably a lot less than you paid for it. That expensive suit in your closet? It's worth about zero on the market, since it was tailored to fit a one-of-one frame. The flat-screen TV on your wall? Sure, it's pretty sweet, but since a newer model is already on the market, it's worth a fraction of what you paid.
None of this is good or bad; it just is. However, this concept messes with us. Just like the Vikings fans angry that the Vikings would trade "a 10th pick for a 5th-round pick," we, too, get messed up with sunk costs. If we're not careful, we can irresponsibly assign more value to something than it's worth, sabotaging our decision-making.
Here's a recent example from my life. One of my friends purchased a house for $400,000 about a year ago. Immediately after buying it, they sank another $100,000 into renovations and improvements. Then the unthinkable happened: one spouse lost their job. They were forced to sell it. After meeting with their real estate agent, they were stunned to learn the house's market value is somewhere in the $425,000-$450,000 range. What?!?! In less than nine months, they spent $500,000 on this house, and it's only worth $425,000-$450,000?
Sunk costs. What they spent matters none. Once the money is spent, it's irrelevant. All that matters is what it's worth now. This really messed them up mentally, and they've made a string of bad decisions. Had they only come to terms with the principle of sunk costs, they would have moved on by now. Instead, they sit in a tough spot.
Always remember that sunk costs are sunk costs. The moment we buy something, we have to let it go and make future decisions on reality's terms.
____
Did someone forward you this post? We're glad you're here! If you'd like to subscribe to The Daily Meaning to receive these posts directly in your inbox (for free!), just CLICK THIS LINK. It only takes 10 seconds.
Rules and Exceptions
Exceptions can be good things, but not everything can be an exception. Exceptions are where people often come off the rails.
Like most households, our house has rules. We put our laundry down the chute. We brush our teeth before bed. We say our prayers at bedtime. Speaking of bedtime, the kids have an 8:45 PM bedtime this school year. Those are rules. Firmly held, but not perfectly held rules.
There are exceptions, though. If the Bears or Chiefs are playing in primetime, the kids can elect to stay up through the game (which probably means a 10:45 PM bedtime). It's a clearly defined exception to a clearly defined rule.
Exceptions can be good things, but not everything can be an exception. Exceptions are where people often come off the rails. Once we open the door to exceptions, our human nature does the mental and emotional gymnastics to carve out all sorts of exceptions. That's why having clearly defined exceptions to clearly defined rules is important.
"Dad, can we stay up late?"
"Are the Bears or Chiefs playing?"
"No, we just wanna stay up."
"No, you know the rules."
Having clear boundaries makes saying "no" easier, but it also makes the exceptions feel special. Also, this really isn't about children's bedtimes. Every aspect of our lives follows this same structure. Rules and exceptions.
When it comes to handling our finances, we need to give ourselves rules. Firm, clear rules. We need structure, boundaries, and definition. Then, we need exceptions. I've said it before, but Sarah and I have one green light to blow through our budget: Giving. If one of us identifies a giving opportunity and we've already expended our allocated giving for the month, we give anyway. No questions asked. No hassle. No issues. We just give.....period. That's a predetermined exception.
But clarity around the exception matters. It would be so easy to take that one simple exception and extrapolate it to other categories. Running low on dining out this month? Oh, that's okay; we'll just make an exception. We're almost out of kids money. No worries, we'll just make an exception. Next thing you know, you've overspent your budget by $900 and yet again failed in that area of life.
This is why rules matter. In our house, if we spend all of our grocery money in a given month, that's it. No exceptions. That can cause frustrating moments, but we aren't going to die. Instead, we dive deeper into the pantry and freezer. We get creative. We find a way. Two important things happen when we honor this firmly established rule: 1) We show ourselves that everything is going to be okay, and 2) We remind ourselves how much it sucks and that we don't want to repeat that mistake again.
Rules and exceptions. Be clear with both. Be firm with both. And remember, you're the author of both, so author rules and exceptions that actually add value to your life.
____
Did someone forward you this post? We're glad you're here! If you'd like to subscribe to The Daily Meaning to receive these posts directly in your inbox (for free!), just CLICK THIS LINK. It only takes 10 seconds.
The Hamsters Are Getting Tired
You know what the problem with more is? Every time we get more, more is still, well, more.
You know what the problem with more is? Every time we get more, more is still, well, more. In behavioral science, one contributing force is called the Hedonic Treadmill. Every time our life changes, that becomes the new "normal." No matter how much money, stuff, or status we attain, it becomes “normal.” Then, like clockwork, we often find ourselves wanting more. I often compare it to a hamster on its wheel. The hamster runs fast but doesn't get anywhere. Then it runs faster, but instead of making more progress, the wheel just turns faster. We're the hamsters!
I often think about a 2018 Harvard study (by Grant E. Donnelly, Tianyi Zheng, Emily Haisley, and Michael I. Norton) on this subject. Researchers wanted to know how happy millionaires are, but more importantly, if they believed more money would make them happier. The researchers divided the millionaires into several cohorts by net worth. Here is how each of these groups rated themselves on a happiness level, on a scale of 1-10:
$1M-$2M Net Worth: 7.8
$2M-5M Net Worth: 7.9
$5M-10M Net Worth: 7.7
$10M+ Net Worth: 8.0
In other words, average happiness was remarkably similar across the four wealth levels, ranging only from 7.7 to 8.0. Here's where the research gets interesting. Among respondents who hadn't already rated themselves a 9 or 10—and who had indicated that some increase in wealth could make them happier—the researchers asked how much additional wealth they believed they would need to reach a 10.
Let's start with the $1M-$2M net worth respondents. Only 13% selected ‘no increase’ when asked how much additional wealth would move them to a 10. Conversely, 77% said they would need at least 2x more wealth to reach a 10.
Next group: the $2M-$5M net worth cohort. Similar to the "poorer" folks, only 13% selected “no increase” to reach a 10. 72% said they would need at least 2x more wealth to reach a 10.
Wait, that's interesting. 77% of the first group said they would need at least 2x more wealth to reach a 10. The second group, despite having almost the same level of happiness as the first and already having materially more wealth, had 72% of respondents still saying they would need at least 2x more wealth to maximize happiness.
How about the $5M-$10M net worth cohort? Again, 13% selected “no increase,” while 70% who received the follow-up question said they would need at least 2x more wealth to reach a 10.
Do you see a trend here? This group, too, had a net worth materially higher than the previous, yet had a similar happiness level, and 70% of those who received the follow-up question believed they needed at least 2x more wealth to reach peak happiness.
Lastly, we get to the $10M+ net worth cohort. I think we can all agree that $10M is a lot of money, right? Only 12% selected “no increase.” Surely this group wouldn't think more money is the answer.....wrong! 72% of people who received the follow-up question said they would need at least 2x more wealth to reach a happiness level of 10.
No matter how much money we have, more is still more. Money, stuff, and status cannot satiate us. Every step of the wealth ladder leaves us wanting more. That's the problem with more. Every time we get more, more is still, well, more.
I have the cure, if you're interested. Opt out of the more game. Stop chasing that which cannot satisfy. Choose a different measuring stick. Instead of chasing money, stuff, and status, pursue meaning, impact, and contentment. It's the only way off the hamster wheel.
____
Did someone forward you this post? We're glad you're here! If you'd like to subscribe to The Daily Meaning to receive these posts directly in your inbox (for free!), just CLICK THIS LINK. It only takes 10 seconds.
Replacing One Stressor With Another
We feel a margin that we haven't felt in a while. One would think this would be the perfect time to harness said margin for the greater good of our family, right? Wrong!
It's a tale as old as time. After grinding and grinding and grinding and grinding, a household will finally pay off that vehicle loan that's been weighing them down. In a single moment, that $400, $700, or $1,000 monthly payment is gone. For years, they repeatedly make these monthly payments at the expense of something they'd rather spend their money on. That $700 could have gone toward travel, dining out, giving, their children's college fund, or retirement. So many different options, yet every month, that $700 was sent to the lender.
Then, on one glorious day, the payment disappears! They own the vehicle free and clear, and that $700/month is immediately and permanently back in their budget to use in valuable ways.
It feels so dang good to be free from that vehicle loan! You probably know what I'm talking about. Life feels a little lighter, the pressure quickly subsiding. We feel a margin that we haven't felt in a while. One would think this would be the perfect time to harness said margin for the greater good of our family, right? Wrong!
Instead, most people make a different kind of decision. That vehicle we've been driving has some miles on it. It's not as new and exciting as it used to be. Their friends, family, and neighbors now drive newer and nicer vehicles. And here's the important part. Since they no longer have a vehicle payment, they have more margin if they want to add a vehicle payment. Therefore, they decide to purchase a new vehicle. And just like that, all of the progress and newfound margin are gone in the blink of an eye. They justify it by saying their payment isn't much different from what it was before, so technically, they didn't go backward. And technically, they are right. That's the problem, though. They didn't go backward... but they didn't go forward. The decisions that stagnated them long ago will keep stagnating them into the future.
For one moment, they had a chance to make a different type of decision. They couldn't undo the past, but they had a golden opportunity to change the future, which can inspire hope and a sense of control over their financial path.....and they whiffed.
This decision pattern is one of the biggest contributors to our society's financial struggles. We like to blame it on other things, like inflation, wage stagnation, the cost of fuel, student loans, and our insane healthcare structure. Sure, these things can affect all of us, but our decision-making foibles around some of our biggest purchases (especially vehicles) are causing undue, unnecessary harm.
Today, I'm encouraging a different kind of decision pattern. When those moments in life happen, when we finally create much-needed margin, resist the urge to fill that gap with another major decision. Instead, embrace the freedom, relief, and opportunity that your newfound margin provides. Future you will rejoice!
____
Did someone forward you this post? We're glad you're here! If you'd like to subscribe to The Daily Meaning to receive these posts directly in your inbox (for free!), just CLICK THIS LINK. It only takes 10 seconds.
Cost After the Cost
After driving that car into my second year of college, I replaced it with a pretty amazing Acura Integra. Black, sleek, stick shift, bangin' rims. To this day, it's my favorite car I've ever driven. I still think about that car. I drove it into my late 20s.
Something dawned on me recently. I was triggered by this thought as I was talking to someone about my personal car chronology. When I turned 16, I had a sweet Camaro. I painted it Carolina Blue, after my childhood idol, Michael Jordan. I loved that car so much; probably too much. However, about 18 months after getting my license, the dumb teenage boy in me made a bad decision, and I totaled the car. It was a very sad day in my world.
After that, I purchased a 10-year-old Honda Civic. It was anything but flashy. In fact, it was as opposite of my Camaro as you could get. It was an ugly brown color and had old-school flip-up headlights. It went from 0-60 in about 15 seconds.
After driving that car into my second year of college, I replaced it with a pretty amazing Acura Integra. Black, sleek, stick shift, bangin' rims. To this day, it's my favorite car I've ever driven. I still think about that car. I drove it into my late 20s.
Back to my epiphany. The highest quality of life and the happiest I ever was was when I drove that old, ugly Honda Civic with the flip-up headlights. It wasn't because I loved that car; I didn't! When I really think about it, that was the only time in my life (until my late 20s) when I didn't feel the burden of ensuring my car was pristine. That was a subversive little cost I never really considered.
Long after we pay for things, we still carry a cost. The cost of taking care of it. The cost of making sure it doesn't get damaged, lost, or stolen. The cost of storing it. The cost of feeling the pressure to use it (after all, we paid good money for x thing). There are costs after the cost, and each silently and slowly takes a toll on us.
I think about this idea when I look at my various possessions. Every possession I own has a cost after the cost. This isn't inherently a bad thing, but it can be when we stack up the costs. This is why materialism is so dangerous. Without knowing it, we're signing up for endless costs after the cost.
As I dip my toes into minimalism, I can feel myself being freed from these hidden costs. Every item that exits my life, and subsequently every item that I refrain from bringing into my life, increases my quality of life more than it decreases my standard of living.
Therefore, the more I watch my quality of life improve (despite my standard of living slipping), I smile. I realize I've found a secret code to life that I never knew existed. Simple is good. Simple is always good.
Today, pay attention to the costs you're carrying well after the initial cost. See how each possession in your sphere puts some form of burden on you. You'll see it....if you're looking for it. Warning: You can't unsee it.
____
Did someone forward you this post? We're glad you're here! If you'd like to subscribe to The Daily Meaning to receive these posts directly in your inbox (for free!), just CLICK THIS LINK. It only takes 10 seconds.
Understanding the Rules
"You expect kids who aren't even old enough to get a job to save tens of thousands of dollars for a car? Most adults aren't able to save for a car."
Or another:
"I think you lost the plot. Between sports and activities, kids don't have time to work. Sports and activities are their work."
I received a flood of feedback after my recent post about our household rule that the kids must save for their own vehicles. In short, many readers found it ludicrous that we would tell 9-year-olds that they must save enough money to buy their own vehicle (while we will match whatever they contribute). One reader had the following thought:
"You expect kids who aren't even old enough to get a job to save tens of thousands of dollars for a car? Most adults aren't able to save for a car."
Or another:
"I think you lost the plot. Between sports and activities, kids don't have time to work. Sports and activities are their work."
Or this:
"Your kids will be driving beaters while everyone else is driving Beamers. You'll pay for counseling later."
I spent 10 years as a volunteer youth group leader. During that time, I often talked a lot with teens and parents about the art and science of paying for college. One particular thread seemed to run through every story. The teens were uber stressed about the entire process. Where should I go to college? How much will it cost? Who will pay for it? What does that mean for my life? The stress level was at 100% during the last two years of high school. Here's what NOBODY said: "I'm stressed because my parents are making me pay for college."
Rather, the stress always came from a lack of understanding. A lack of clear process. A lack of conversation. These teens were mere months away from graduating high school, yet had no idea what the implications and consequences were of any decision being made. There were no rules. If their parents had established rules, processes, and expectations, these teens would have been far less stressed, even if they were told they had to pay 100% of the cost. The stress didn't come from the cost; it came from the lack of rules and clarity.
Back to tasking children to save for vehicle purchases. The cost isn't punishment; not giving them clarity is. Giving our kids rules, expectations, and process is a gift. It allows them to understand the lay of the land and make decisions accordingly. Or, here are the wise words of my friend Randy, who was required to personally pay for any fun extras while he was a kid growing up in a lower-income family:
"I did not resent it because I understood the rules and self selected what was important to me."
"I understood the rules." Right there. Randy didn't have spoils dropped in his lap. He was required to self-fund anything extra. Despite the fact he had to pay for all his extra stuff (while many of his friends probably didn't), he respected the rules and navigated them accordingly. Beautiful. Side note: Randy went on to become a tremendously successful (and generous) businessman.
Pain and sacrifice are not unkind; vagueness is. Therefore, let's not allow entitlement or spoiling supercede clarity and responsibility. Have an awesome day!!
____
Did someone forward you this post? We're glad you're here! If you'd like to subscribe to The Daily Meaning to receive these posts directly in your inbox (for free!), just CLICK THIS LINK. It only takes 10 seconds.
Who’s the Old Guy With the Green Face?
The morning quickly derailed from the status quo. I opened my web browser and saw that the headline I'd seen at the library wasn't just odd; it was the beginning of what would become one of the greatest tragedies I'd ever experience. The day was 9/11/2001.
Beautiful day! The sun is shining, and it's always enjoyable to be on campus. I needed to grab a book from the library before I headed to work. While I was checking out, I saw a weird headline on a computer screen. Odd. Never mind, though, as I was cutting it close and needed to sprint to work. I quickly arrived at my destination, a buzzing computer lab in a dungeonous building on the west side of campus. It wasn't the most exciting job in the world, but essentially getting paid to do my homework was a win/win. The morning quickly derailed from the status quo. I opened my web browser and saw that the headline I'd seen at the library wasn't just odd; it was the beginning of what would become one of the greatest tragedies I'd ever experience. The day was 9/11/2001.
Yesterday was the 25th anniversary of 9/11. I saw a few video clips about it, but I wasn't thinking too much about it. However, while I was on the way to a meeting, I realized that I was driving to the very city I experienced that day 25 years ago: Ames, IA. I was 20, a sophomore at Iowa State University.
Back to my drive. As I headed north on the Interstate, memories of that day flooded back. Then, it dawned on me that I had some extra time at my disposal. In what might be considered a morbid ritual, I decided to retrace my steps from that day 25 years ago.
I started at the library. Although the main lobby has since been completely renovated and reorganized, I could still see (in my mind) where the previous check-out desk had been. I could see that old, clunky computer monitor with an image of a plane flying into an iconic building. Just as I stepped out of the library, I ironically stumbled into a temporary 9/11 memorial on the lawn.
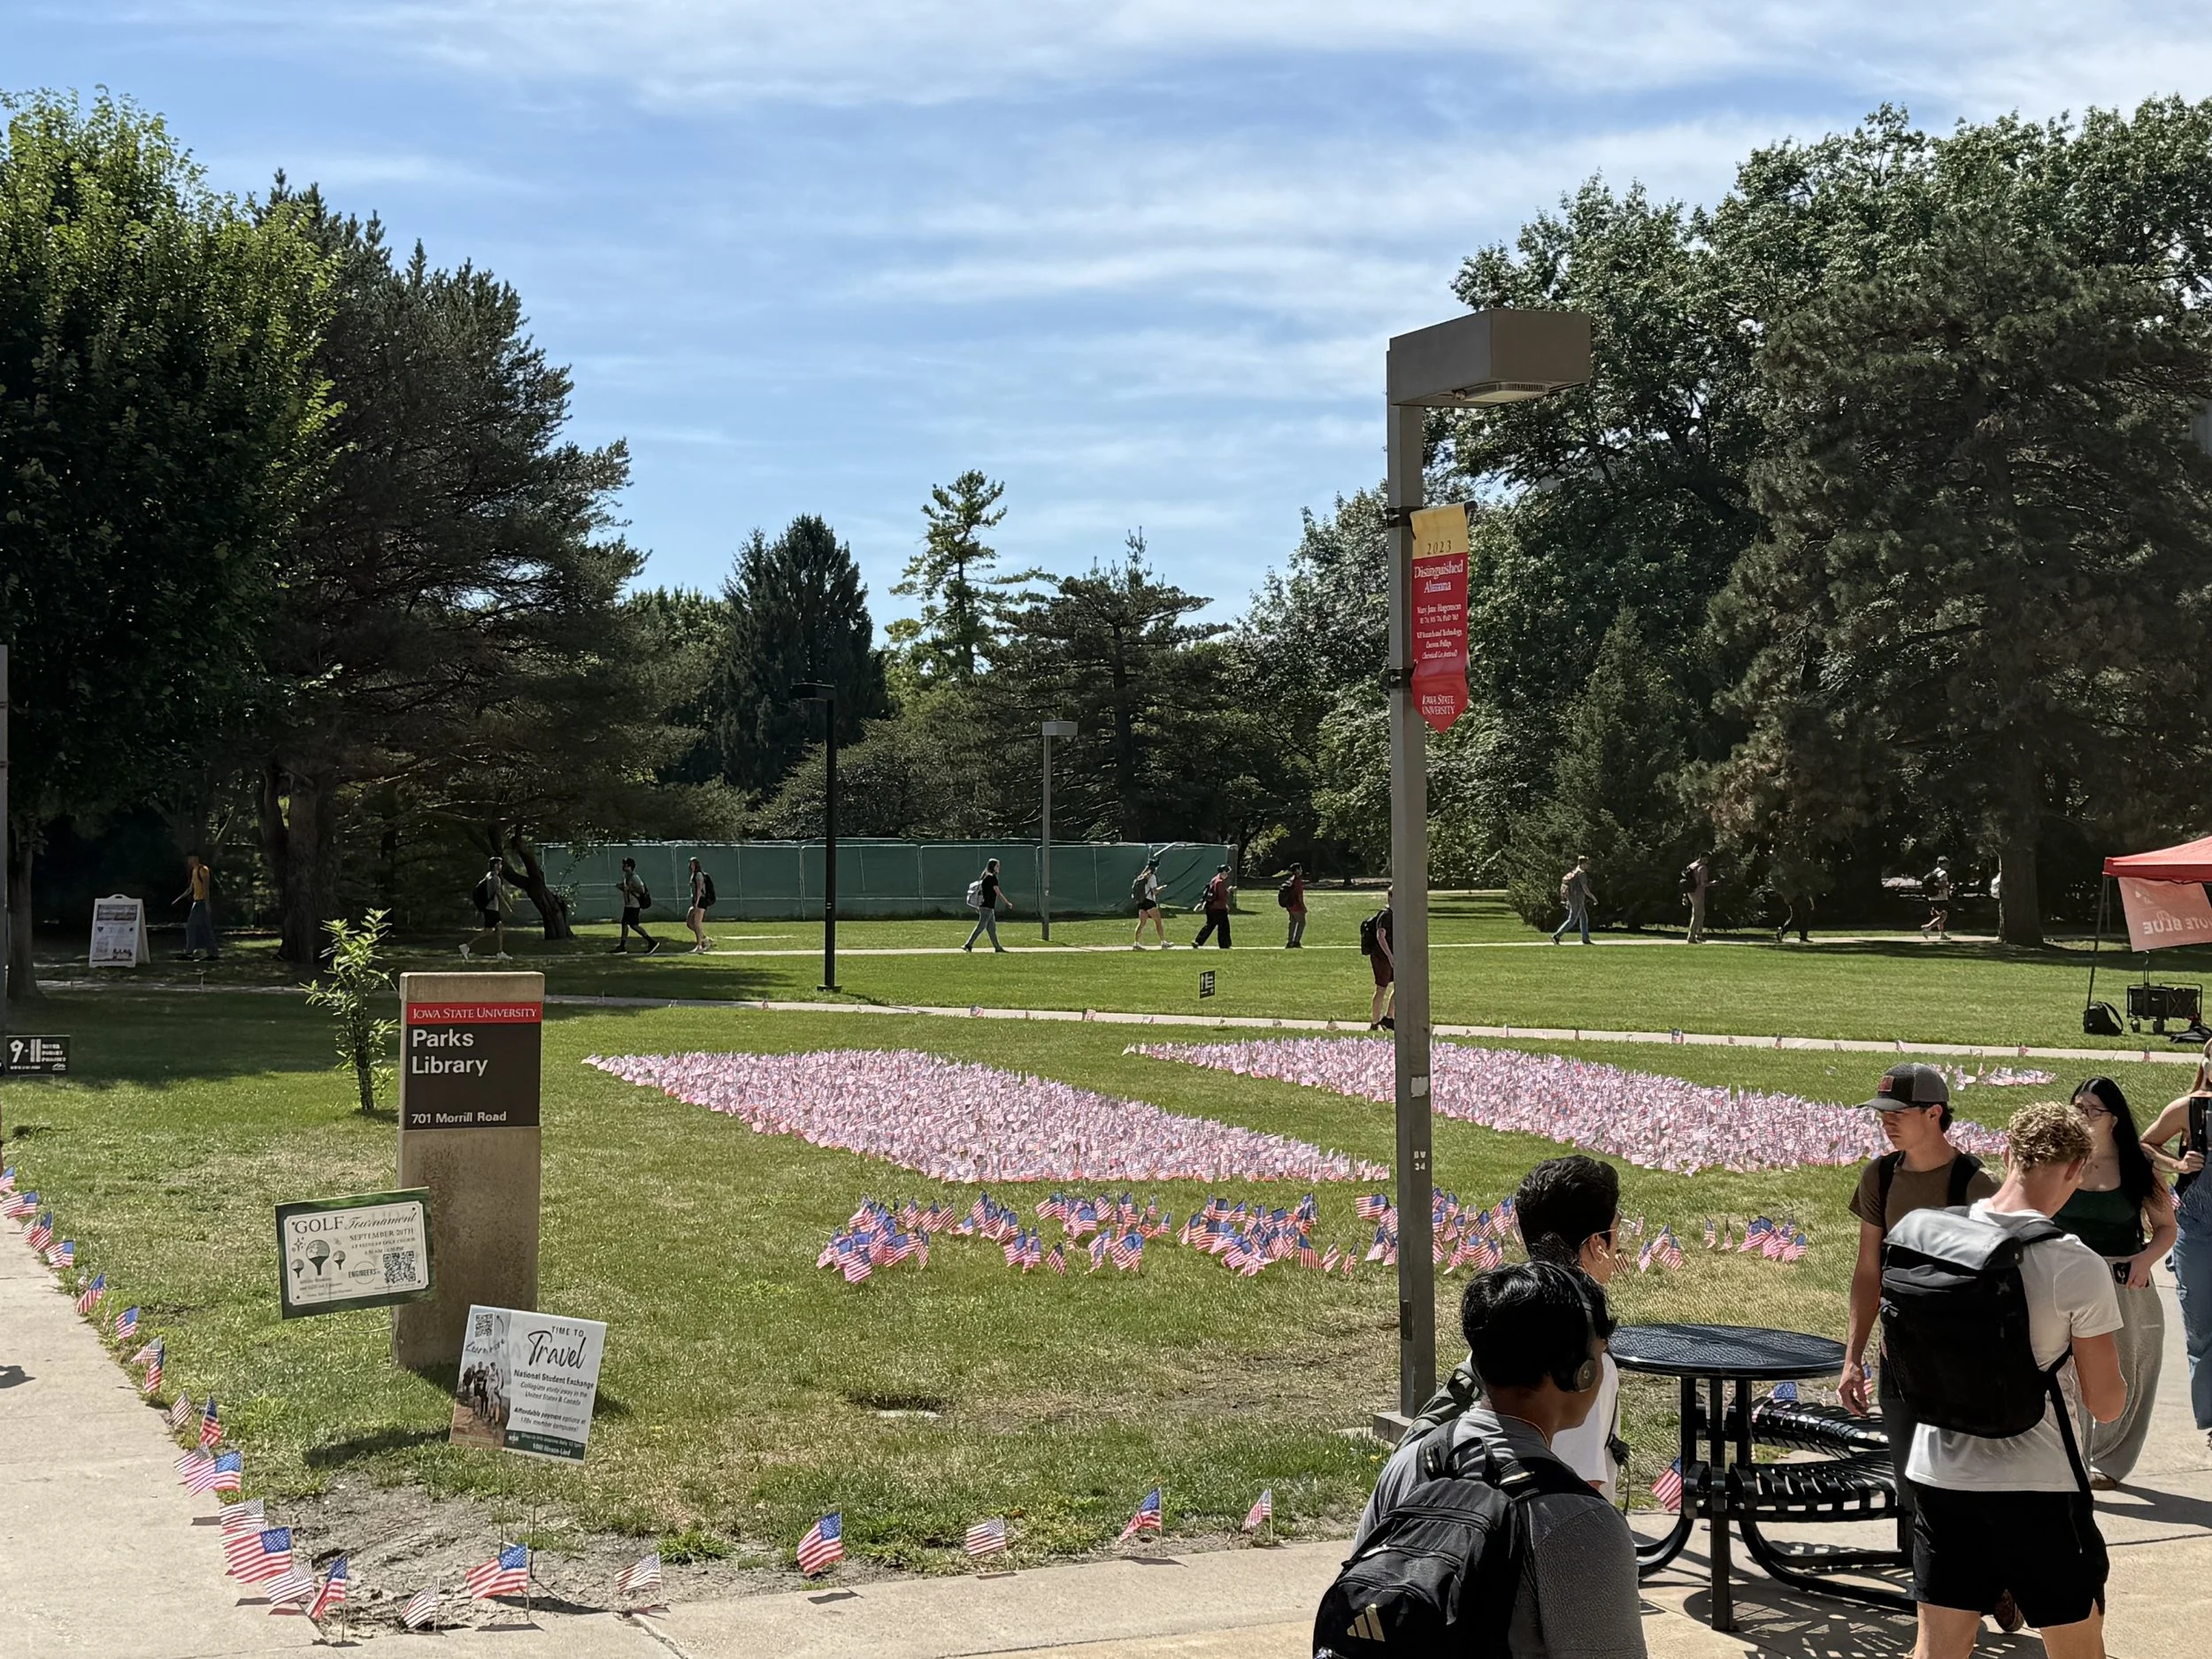
After taking it in, I scurried to the old dungeonous academic building just as I did that fateful day. Do computer labs still exist? Is that building even still in use? Sure enough, the computer lab was still there! There were a lot of people milling about, so I didn't awkwardly stay too long. I found the exact location where I witnessed the horrors of 9/11 unfold.
The entire time, I had a pit-in-my-stomach feeling. My chest felt tight. My thoughts were racing. I probably looked unwell. My face was probably somewhere between pale and green. It felt like a fever dream. I could only imagine what all those young people were thinking. "Who's the old guy with the green face?" Needless to say, it was a surreal experience; I'm glad I did it. I can't help but think about how much that day shaped the journey I've taken over the past 25 years.
Whether we like it or not, who we are and how we think is shaped by what we experienced throughout our journey. Every quirk, opinion, perspective, and behavior you have has been influenced by what's happened to you. That's neither good nor bad, but an inescapable reality. There's more to discuss about this topic in a future post, but in the interest of time and space, I want to challenge you with something today. Think about a weird or unhealthy habit or behavior you have around work or money. Now, look back on your journey and figure out where it came from. It's right there in front of you. Often, the answers that help us get to a better place lie in our past....if we can find it. More to come.
____
Did someone forward you this post? We're glad you're here! If you'd like to subscribe to The Daily Meaning to receive these posts directly in your inbox (for free!), just CLICK THIS LINK. It only takes 10 seconds.
The $1,500 Haircut
This is the story of a $1,500 haircut. A friend of a friend loves getting her hair done. Cut, color, extensions - at a high-end salon - for the low, low price of $1,500. To me (and probably you), this is a staggering amount to spend on a haircut. Why would anyone do something like this? "Well, I can afford it, so why not?"
This is the story of a $1,500 haircut. A friend of a friend loves getting her hair done. Cut, color, extensions - at a high-end salon - for the low, low price of $1,500. To me (and probably you), this is a staggering amount to spend on a haircut. Why would anyone do something like this? "Well, I can afford it, so why not?"
I can afford an entire semi-load of Hostess Oatmeal Creme Pies, but it doesn't mean I should. This is where so many of our financial decisions come off the rails. We often justify questionable decisions by saying we can afford them. Afford, on what grounds? In the classical sense, do I have enough money in my bank account to trade for xyz good? If so, technically, I can afford it.
However, we often underestimate the opportunity cost. Sure, I could buy an entire semi-load of Hostess Oatmeal Creme Pies (or a $1,500 haircut). Doing so probably wouldn't destroy my finances. But the better question is: "Is there something I'd rather do with this money?"
Every dollar we spend on something is one dollar we can't spend on something else. If I could talk to this woman with the glorious hair, I wouldn't ask her if she can afford the haircut. I'd ask her if there's something better she would do with that money. Everything is about the opportunity cost, including her haircut and my Oatmeal Creme Pies. There's nothing inherently wrong with her spending $1,500 on a haircut, but based on my coaching experience, I'm guessing there are areas of her life that are lacking.....frustratingly so. We humans have a way of sabotaging ourselves like this.
People tend to fall into one of two camps:
Person A: Do I have the money to buy this thing I want?
Person B: What is the best use of this money?
Both people might buy the same item, but the second person does the mental math to account for the opportunity cost. If we're wise, every decision is framed through the lens of opportunity cost. And, no, the goal of this mental exercise isn't to figure out which decision will create more monetary gain. This isn't about spending being bad and saving being good. Rather, this is about giving our decisions an honest look to determine how we can maximize our meaning, fulfillment, and impact. Sometimes, it means buying the cool thing. Sometimes, it means choosing a different option.
Perhaps you already do this. If so, you're far wiser than most. If not, today is a fantastic day to start looking at your decisions through the lens of opportunity cost. It changes our relationship with money, and it helps us focus on what's truly important to us.....even if it's a $1,500 haircut.
____
Did someone forward you this post? We're glad you're here! If you'd like to subscribe to The Daily Meaning to receive these posts directly in your inbox (for free!), just CLICK THIS LINK. It only takes 10 seconds.
Chess vs. Checkers
He thought he won, but he was playing checkers while the dealership was playing chess. The salesperson knew which buttons to push, and thoroughly pushed them.
A friend recently saved up about $35,000 to purchase a vehicle. He knew what he wanted, educated himself, and walked into the dealership armed with the information to buy a slightly used vehicle. The plan was made, and now it was time to execute!
I called him a few days later. "How did it go?!?! Did you get what you wanted?"
"I ended up with an even better deal!"
Oh man, I was dying to hear more. I was proud of him for nailing this one. After all, he had worked so hard to save that cash. Then, he shared the story......
He walked in with a plan to pay $35,000 in cash for a 3-year-old model he had his eyes on, but walked out with a brand-new model with a $52,000 price tag. What?!?! Wait, where's the better deal? "They offered me 1.95% for a 72-month loan.....that's practically free money! I make much more than that on my high-yield savings, so I'm actually making money on the deal."
Here's how he framed it:
If he had paid cash, it would have cost him $52,000.
With a $765 loan payment for 72 months, it would cost him only $55,000 over 6 years. Just $3,000 more for the privilege of stringing it out for 6 years.
Now, he can keep his $35,000 in his high-yield savings account. At 3.5% interest, he'll make $1,200 per year, or $8,600 over the next 6 years.
$8,600 of interest earned minus $3,000 of interest paid = He's coming out +$5,600 on the deal. Boom!
He couldn't have been more excited. He felt like he just won the game. However, I don't think he's looking at this through the proper lens. He didn't come out $5,600 better on the deal. He walked in hoping to spend $35,000 on a vehicle and walked out committed to spending $55,000. That feels more like spending $20,000 MORE than planned.
Further, he now has to tell his wife that he just signed up for a $765/month vehicle payment just one year after promising each other they wouldn't go back to playing the debt game (after grinding their way out of the last one). As he put it, adding $765/month to the monthly budget won't be simple, "but the deal was too good to pass up."
He thought he won, but he was playing checkers while the dealership was playing chess. The salesperson knew which buttons to push, and thoroughly pushed them.
Here's the thing. My buddy is a smart dude. In fact, I'd dare call him brilliant in many ways. He has a truly gifted mind, and he's tremendously successful at his craft. However, he's also human. He's not immune to the psychological games being played on us on a daily basis.
It's so easy to get played. We think we're winning, but we're playing checkers while the person on the other end is busy playing chess. We need to be mindful. And in the world of personal finance, debt is often used as a creative tool for the chess player.
Stay vigilant, my friends! These are winnable battles, for sure, but we must keep our wits about us as we navigate this world of finance. One day, one decision at a time. You got this!
____
Did someone forward you this post? We're glad you're here! If you'd like to subscribe to The Daily Meaning to receive these posts directly in your inbox (for free!), just CLICK THIS LINK. It only takes 10 seconds.
Numbing the Pain Sensors
"There's no scenario where I would spend $35,000 of cash on a vehicle. That's why I want to finance it."
"How much should I spend on a car?" a friend asked me recently.
"How much cash do you have saved for a car?" I asked in return.
"About $18,000, give or take."
"Then I would spend $18,000 or less."
He stared at me for a moment, pondering what to say next. "But the car I want costs $35,000. How do I know if I can afford that?"
"It's pretty simple. You'd be able to afford it if you had $35,000 saved up. But since you only have $18,000, you definitely can't afford it."
He stared again. "What should I do, then?"
"Either buy a $18,000 vehicle now, or keep saving until you can afford a more expensive vehicle."
I think we complicate things too much, especially with vehicle decisions. Then, we add the psychological warfare of debt into the mix, and we get completely twisted up. That's where my friend went next.
"There's no scenario where I would spend $35,000 of cash on a vehicle. That's why I want to finance it."
See what's happening here? The debt pollutes our decision-making. He just admitted he would never exchange $35,000 of cash for a vehicle (because it's a lot!!!!), but he would mindlessly sign papers to finance $35,000, $45,000, or even $55,000. He said he'd have no problem financing a vehicle up to about $70,000, but wouldn't feel comfortable spending more than $20,000 of cash on a vehicle.
See the problem here? The debt numbs the emotional triggers that tell us something might be a questionable-to-poor decision. He would have an emotional breakdown paying $25,000 for a car, but he wouldn't flinch at spending $65,000 with debt. That's how we Americans have enslaved ourselves in crippling debt payments.
If we really want to make proper choices, we'd take debt out of the mix and look at everything through the lens of cash. Are we really willing to pay for something, or are we just trying to numb our pain sensors by slowly bleeding ourselves out over time?
Update: My buddy called me a few days later. After much consideration, he realized that he was, in fact, being heavily influenced by the debt. There's zero chance he would ever pay cash for an expensive vehicle, and the debt merely allowed him to "cheat the system," in his words. He said he'll likely save up for a few more months and pay cash for a vehicle in the mid-twenties range. I think that's a wise decision! His future self will thank him for that one.
Don't let debt numb you to the realities of your decisions. You'll think more clearly, make better decisions, and create far more freedom in your life. It's worth it.
____
Did someone forward you this post? We're glad you're here! If you'd like to subscribe to The Daily Meaning to receive these posts directly in your inbox (for free!), just CLICK THIS LINK. It only takes 10 seconds.
Ignorance Is Not, In Fact, Bliss
He's not dumb. He's not a liar. He's not bad at math. He's not trying to pull my leg. This is how we humans mentally accrue math that spans several smaller numbers. We grossly miscalculate the cumulative impact of a string of decisions.
In working with hundreds of families over the years, one thing is consistently true: We humans have a very poor ability to mentally track how much we spend on x category each month. Example: I recently asked a family how much they spend on dining out each month: "Probably $200, $300 tops."
"Well, we're about to find out," I responded. "Out of curiosity, why do you say $200-$300?"
"Because we kinda track it already. I just know what we spend."
"Kinda tracking is the same as not tracking at all," I said.
Fast forward to the end of the following month, and they had formally tracked all their spending: $913. More than triple their top-end estimate!
"That can't be!" the husband exclaimed. "I know what we spend, and we don't spend $900!"
He's not dumb. He's not a liar. He's not bad at math. He's not trying to pull my leg. This is how we humans mentally accrue math that spans several smaller numbers. We grossly miscalculate the cumulative impact of a string of decisions.
Ignorance isn't bliss. A rough understanding is the same as no understanding. We don't need to be number police and obsess about everything in our lives, but if we want to get better in a certain area, we need to educate ourselves. This is always priority #1 for my coaching clients. There are three steps to getting right with money:
Gain awareness
Gain control
Gain traction
We can't gain control or gain traction until we've first gained awareness. Here's the good news: Gaining awareness doesn't cost money, require special skills, or necessitate a large time commitment. All it requires of us is care and intentionality.
Here's my encouragement. If you're not fully locked into a budget yet, pick a category you want to improve on. For the next calendar month, log every dollar you spend on that category. Use the Notes app on your phone if you'd like. You don't even need to log it to the penny; round to the nearest dollar. Date: Amount. Date: Amount. Date: Amount.
If you commit to the practice for even just one month, you'll gain insights about yourself that will arm you to succeed next month, the month after, and so on. Simple, effective, game-changing. Note: this isn't about spending less; it's about spending better. After we assess what we're actually spending, we can determine if that's a good amount in the context of our lives. Maybe we should spend more! Maybe knowing how much we're spending can help us make better and healthier decisions in the other categories. Maybe we want to put some guardrails in place. So many opportunities for improvement, all stemming from becoming aware.
This isn't supposed to be some magical, earth-shattering idea. Rather, a simple idea that's easy to execute and will provide far more value than it will cost you. Happy tracking!
____
Did someone forward you this post? We're glad you're here! If you'd like to subscribe to The Daily Meaning to receive these posts directly in your inbox (for free!), just CLICK THIS LINK. It only takes 10 seconds.
Know Thyself
And for the last 1,400 days, I know this button as the source of much heartache. With a simple click, I could unearth the names of those three people who no longer value this blog enough to receive it each day.
I'm a firm believer in having a brutally honest self-awareness of our own personal foibles, triggers, and weaknesses. For example, I know I can't gamble in any form. I dabbled in sports gambling when I was in college, and within just a few days, I realized it could easily get away from me. Thus, I haven't even considered gambling a single cent in approximately 25 years. I have a keen self-awareness of this nuance, and I act accordingly. I don't believe that makes me weak; rather, it makes me wise.
Some things in our lives are just unhealthy for us.....period. It doesn't mean those things are unhealthy in nature, but for whatever reason, they are unhealthy for us. Again, that doesn't make us weak; it makes us self-aware....and hopefully wise.
Here's another weakness of mine. This button right here:
This button lives on the summary page of every blog e-mail that gets sent into the world. For the last 1,400 days, this button has lived on my phone screen. And for the last 1,400 days, I know this button as the source of much heartache. With a simple click, I could unearth the names of those three people who no longer value this blog enough to receive it each day.
There's nothing like clicking on this button to realize one of the closest people in your life just went out of their way to terminate your work from entering their life. It sounds dramatic, I know! But for whatever reason, this one little button has the power to create unprecedented pain and suffering in my life.
Therefore, knowing this about myself, it's a button I'm unwilling to press. That doesn't make me weak; it makes me wise. For all I know, the three people who went out of their way to rid me of their digital life a few days ago could have been my wife, sister-in-law, and best friend. Who knows!?! Not me! I always know how many people receive and read my blog each day, but I couldn't tell you who they are. I allow that to remain a mystery to me (aside from the thoughtful e-mail replies I receive), and instead, simply focus on writing what I'm called to write.
Know thyself. There are things in your life that are unreasonably tempting, troubling, and risky for you. Things that might not be inherently bad or wrong, but bad or wrong for you. Have the self-awareness to recognize them and the humility to make the right decisions. Often, these little decisions free us up to live the life we're called to live. A life full of much more meaning and a lot less turmoil. Free yourself! Be wise! A few simple decisions could unlock the better you deserve.
____
Did someone forward you this post? We're glad you're here! If you'd like to subscribe to The Daily Meaning to receive these posts directly in your inbox (for free!), just CLICK THIS LINK. It only takes 10 seconds.
Not Weird At All
We must take the terrible with the great if we want the good. That's the secret to investing.
We're going to swing the pendulum back to the money side today, which was spurred by a series of conversations I had with friends over the past few days. Specifically, they asked me about the U.S. stock market. One friend pointed out that if the year ended today, the market would be up about 13% for the year. Their understanding is that the stock market is supposed to give us an 8%-10% annual return. Further, based on their recent memories, they can't recall in recent history when the market actually finished a year in the 8%-10% range.
"Isn't that weird?" he asked. He was right about the recent past. Here's what the total U.S. stock market has looked like over the past 10 years:
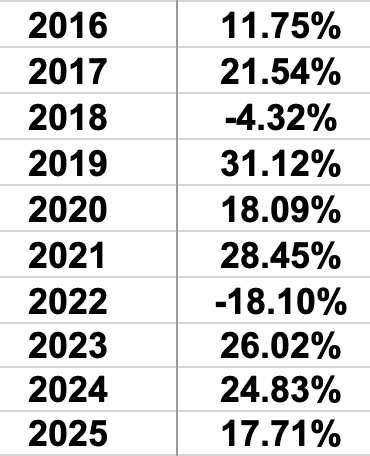
This decade-long span has provided annual returns ranging from -18% to +31%, with no single year falling in the 8%-10% range. It's safe to say that the stock market seems erratic.
This isn't a last-decade phenomenon. Over the past 156 years, only three single years have landed in the 8%-10% range: 1912, 1916, and 1993. The other 153 years fell outside of this range, often ridiculously so. However, when we step back and factor all the wild years into one cohesive data set, the U.S. stock market has averaged 9.25% over those 156 years.
In other words, getting less than 8%-10% in a single year isn't a bad thing. Losing money in a single year isn't a bad thing. Feeling pain in a single year isn't a bad thing. Rather, it's the admission price to earning that long-term 8%-10% we're striving for. We must take the terrible with the great if we want the good. That's the secret to investing.
How does this relate to meaning? In my coaching and teaching, I see far too many people sweating and stressing over this investing stuff, so much so that it hinders their ability to live joyful and meaningful lives. My challenge for people today is to simply let the market be the market (goods, bads, and everything in between) and pursue a meaningful life. Be patient, quit looking at your investment accounts, and don't let the news bum you out. In the short run, it might feel scary, but in the long run, we will prevail.
Have an awesome day!
____
Did someone forward you this post? We're glad you're here! If you'd like to subscribe to The Daily Meaning to receive these posts directly in your inbox (for free!), just CLICK THIS LINK. It only takes 10 seconds.
An Experiment In Leisure
I often write about my qualms with our cultural obsession with retirement. Specifically, our collective pursuit of a life of leisure. In theory, this is the secret to happiness and satiation, but in reality, it's just empty calories.
I often write about my qualms with our cultural obsession with retirement. Specifically, our collective pursuit of a life of leisure. In theory, this is the secret to happiness and satiation, but in reality, it's just empty calories. Instead, what we should all be pursuing is a life filled with meaning. No, leisure isn't a bad thing, and we should all find ways to enjoy leisure along the journey. However, leisure for leisure's sake is ultimately an unsatiating endeavor.
This brings me to an experiment I recently conducted. In May, I decided to carve out a little extra time for leisure this summer. A few more trips, a few more low-key days. I didn't plan these trips and events methodically, but rather, slotted them in wherever they fit. The accidental consequence was a three-week stretch that included the following:
5 days in NYC with the family.
A few days at home.
A 3-day conference in Chicago to learn, grow, and enjoy.
A few days at home.
8 days on the lake with the family.
I'm currently in the middle of my lake time with the family. We've had a great time together. Heck, I enjoyed NYC and the conference as well. It's all been wonderful. Just one problem: It's too much leisure! I can't even explain how much I miss my normal rhythm of work, productivity, and impact. I'm ready to get back into the grind.
Leisure is amazing, but just like chocolate chip cookies, Old Fashioneds, and the free breadsticks served at Fazoli's, too much of a good thing isn't a good thing. Leisure has its place, and that's properly sandwiched between good work.
These last three weeks have proven to me once again that traditional retirement is not the ticket to happiness. Leisure, without having something to leisure from, just doesn't hit as hard. As many of my friends and I have gotten older, I've explored this topic with many people. What should "retirement" look like? For me, it will likely take the form of full-time work, but with more trips. Maybe three weeks on, one week off. Or six weeks on, two weeks off. Maybe it will be one full-time job. Maybe it will be a series of smaller, part-time jobs. Maybe it will be running my companies. Maybe it will be doing consulting work, speaking, and/or writing. Maybe it will be volunteering.
I have no idea what that Travis will have in store for him. But one thing I do know is that leisure for leisure's sake is not in the cards. Leisure, yes. But leisure sandwiched between good work. That's the ticket.
____
Did someone forward you this post? We're glad you're here! If you'd like to subscribe to The Daily Meaning to receive these posts directly in your inbox (for free!), just CLICK THIS LINK. It only takes 10 seconds.
Anchoring
Why do you spend $x on a certain category each month? The answer probably isn't too deep, and it likely has something to do with the fact that's what you always spend on said category each month. But why? Because that's the way you've always done it.....or at least that's the way you've done it long enough for it to be ultra-normalized.
Why do you spend $x on a certain category each month? The answer probably isn't too deep, and it likely has something to do with the fact that's what you always spend on said category each month. But why? Because that's the way you've always done it.....or at least that's the way you've done it long enough for it to be ultra-normalized.
Now, maybe that's how much you should spend on that category. Maybe it's the perfect number, but probably not. It's probably not even close to the right number. However, we choose that number because we're anchored by the past. We're so accustomed to spending that amount of money each month that we don't even question what it should be. Should it be more? Should it be less? We haven't even considered it!
Once in a while, I'll ask a client who is fully locked into their finances to complete a fun exercise. Instead of basing their next month's budget off what they've done in the past, I'll give them a blank budget with all their utilized categories, and force them to build it from scratch.
You might think they would largely end up in the same place as what they already do every month. You'd be wrong! Most times, this exercise yields completely different results. It's amazing what happens when we remove the anchors from our decisions, and instead, assess each category as it actually lives in our lives. There's a purity in this exercise. It allows us to remove the fog of complacency, the bias toward past realities, and the frictionless non-decision of maintaining the status quo.
I actually think Sarah and I are in need of this exercise soon. Our monthly budgets haven't changed much in the past 18 months, and I don't think that's a good thing. Instead of anchoring ourselves in "normal," we should look at each category through the lens of our current reality. I have a feeling many changes will be made. I encourage you to try this exercise, too!
____
Did someone forward you this post? We're glad you're here! If you'd like to subscribe to The Daily Meaning to receive these posts directly in your inbox (for free!), just CLICK THIS LINK. It only takes 10 seconds.
The Timing Couldn’t Have Been More Perfect
I received an amazing text yesterday! A casual friend texted me out of the blue, as he does from time to time. He loves talking about finance, investing, and the stock market. Here was his text: "When do you think the stock market will turn around and recover?"
I received an amazing text yesterday! A casual friend texted me out of the blue, as he does from time to time. He loves talking about finance, investing, and the stock market. Here was his text: "When do you think the stock market will turn around and recover?"
That's an interesting question.....and an amazing text! What makes it an amazing text, you might ask? Yesterday, the U.S. stock market hit an all-time 155-year high, eclipsing the prior all-time high achieved on June 2nd. Never in history has the U.S. stock market been at a higher level. At the same time, millions of people, including my friend mentioned above, have been led to believe that everything in our country has fallen apart, including the stock market.
It goes to show just how easily people can be manipulated by the news and social media. Even though we all live in a certain reality, all people have to do is repeat the lie enough times for us to believe it. That concept has been studied and practiced for centuries, and this is just a modern version of it.
Year-to-date, the stock market is up by more than 13%. This comes on the heels of +18% in 2025, +25% in 2024, and +26% in 2023. I think the better question we should be asking is, "When will the market crash again?"
My most reasonable answer is, "soon," but nobody knows. Nobody knows.....especially the news and social media. If that's true, what shall we do? I propose we do nothing. The stock market always crashes. That's a feature of a healthy and functioning market. Therefore, I propose we all just take a deep breath, stop doomscrolling, and live our lives. If the market crashes, it crashes. Every crash in the history of our great country has been followed by a period of growth, eventually dwarfing the previous all-time highs.
I hope you find this encouraging, as many people are anxious right now. No, the market hasn't crashed. Yes, it will crash in due time. No, you shouldn't worry. Just stay the course, live meaningful lives, and let the chips fall how they may. And if history can tell us anything, the chips always fall in our favor....eventually.
____
Did someone forward you this post? We're glad you're here! If you'd like to subscribe to The Daily Meaning to receive these posts directly in your inbox (for free!), just CLICK THIS LINK. It only takes 10 seconds.
The Moment I Knew
"While we're on the road, the two people who aren't driving spend time contacting and pitching everyone. Old clients, warm prospects, cold prospects.....everyone."
One of my commercial clients is comprised of three young, talented, hungry owners. They are brilliant at their craft, but not accomplished business owners.....yet. In the midst of trying to grow their newish business, they lost a key client. Many of their aspirations for near-term growth skidded to a halt, replaced by a sudden need to piece together a few deals to stay afloat.
One of them recently reached out with a question. I immediately called them back and happened to catch them while they were driving across the state for a work project. One of the owners said something to me that quickly caught my attention. They recently purchased a mobile Starlink unit so they have high-speed internet in their vehicle on road trips. Why? "While we're on the road, the two people who aren't driving spend time contacting and pitching everyone. Old clients, warm prospects, cold prospects.....everyone."
That's the moment I knew they were going to be just fine. Being brilliant at our craft isn't enough. Often, it takes a mastery of our craft combined with a relentlessness and humility to just go for it. What makes these three individuals unique is that they are impervious to failure. They could have 1,000 doors violently slam in their face, only to knock on the 1,001st door with full confidence that it will be a "yes."
I wish I had that same relentlessness gear they do. I've been thinking a lot about that conversation, and it's forced me to look in the mirror with my own attitude and approach. For as successful as I feel like I've been, I can't help but wonder what things would look like if I developed a gear like these three have. It's an interesting thought experiment, and it pushes me out of my comfort zone. Maybe you need a similar nudge today. A nudge to develop a relentlessness and motor to keep going, regardless of how many shut doors you encounter. Something to think about as you go about your day. Have an awesome one!
____
Did someone forward you this post? We're glad you're here! If you'd like to subscribe to The Daily Meaning to receive these posts directly in your inbox (for free!), just CLICK THIS LINK. It only takes 10 seconds.
Chicken or Egg?
I recently stumbled upon a heated online conversation on a social media platform. The original poster posed a question: "If so many people are struggling right now, why are there so many people with brand-new vehicles parked in their driveways?"
I recently stumbled upon a heated online conversation on a social media platform. The original poster posed a question: "If so many people are struggling right now, why are there so many people with brand-new vehicles parked in their driveways?" It seemed counterintuitive, as these new vehicles are presumably evidence that people are doing well.
Let's just say the comments were lively. Hundreds of people chimed in, positively confirming that most people are, in fact, doing great. The commenters believed they, individually, were simply part of the small share of people who are struggling, while everyone else is thriving.
I have news to break to them (and anyone else who will listen). Those brand-new vehicles sitting in people's driveways aren't evidence that people are doing great. Rather, those same vehicles are one of the primary culprits for why people are struggling so much. People's vehicles are putting them into a financial grave, month after month.
I recently met with a successful-looking couple who, from the outside, appear to have it all put together. They are fit, their kids are cute, their house is immaculate, they have good jobs, and they both drive new vehicles. The subject of the conversation? How they can stay financially afloat and not lose everything. Truth be told, their monthly finances didn't contain many red flags. Lots of normal, but not outlandish spending allocations. However, there were two major red flags.....and both were parked in their garage:
His vehicle: $1,100/month payment
Her vehicle: $850/month payment
Total vehicle payments of $1,950. In my brain, that's called a mortgage payment. Two thousand bucks for vehicles!?!? Both assured me that 1) they can afford them, 2) they are perfectly reasonable vehicles, and 3) everyone else has at least as nice vehicles as they do.
They aren't alone. This is a dynamic I see every single week in my coaching work. I've met with hundreds of families, and vehicle tension is the leading contributor to financial pain, suffering, tension, stress, and destruction. Not a lack of income, student loan debt, a failure to budget, or limited financial literacy. Vehicles. Vehicles are literally milking an entire society dry.
Many people who read this piece will roll their eyes at me. This topic often draws the ire of those who digest my content daily. That's okay, though, as this message needs to be shared over and over and over. I so badly want people to live a quality of life, and if I can get them to make different decisions in this vehicle department, I strongly believe it will have a direct positive impact on their quality of life.
We need more humility. We need more patience. We need to care a whole lot less about what others think. That's the ticket to some beautiful things in our lives. Please don't allow a vehicle to play a significant role in your journey. It can play a role, but not a leading role. You deserve better; much, much better!
____
Did someone forward you this post? We're glad you're here! If you'd like to subscribe to The Daily Meaning to receive these posts directly in your inbox (for free!), just CLICK THIS LINK. It only takes 10 seconds.
Outgrowing Your Structure
I recently met with a couple who are becoming progressively more frustrated with their finances. This seems counterintuitive, though, as they are making far more money than they ever have before. Why, then, are they getting frustrated? It's pretty simple: The current complexity of their life has outgrown their financial structure.
I recently met with a couple who are becoming progressively more frustrated with their finances. This seems counterintuitive, though, as they are making far more money than they ever have before. Why, then, are they getting frustrated? It's pretty simple: The current complexity of their life has outgrown their financial structure.
Translation: The way they used to handle finances worked well then, but not so much anymore. It was easy to wing it and be more casual when there was less income and fewer obligations. However, life is getting more complicated, and the old way of doing things seems inadequate at best, destructive at worst.
It reminds me of a similar situation we're having at Northern Vessel. Nearly four years in, it's safe to say our business looks a little different than it once did. During a recent team dinner (celebrating one of our team members who left to pursue a new dream), it was time to pay the bill. TJ couldn't be there, so it was on me to pay. Unfortunately, I forgot to ask TJ for the debit card. At the last second, Jack swooped in to pay the bill, somehow having TJ's card in his wallet.
That's right, we literally have only one debit card. The entire company has been operating with one debit card and one checkbook. We have tens of thousands of dollars in monthly expenses, yet the entire operation rests on one debit card and one checkbook. We've outgrown our structure, and we're experiencing the consequences.
Whether it's the family I mentioned above or a company like Northern Vessel, we must iterate on the structure as we grow. What once worked might not be adequate in the new season of being. Taking the "this is the way we've always done it" approach is a surefire way to end up in a bad place. Therefore, we need to give ourselves permission to evolve, adjust, and continue to find better ways to handle ourselves.
Some of you are handling your family's finances the same way you did when you were young, single, broke, and fresh out of college. Except now, you have a spouse, kids, a house, and multiple incomes. It might be time to update the structure! For some of you, simply upgrading the way you do things might be the ticket to significantly better outcomes. It doesn't matter if you've done it the same way for 20 years.....it might be time to adjust.
Never be scared to make changes. As life becomes more complicated, find ways to simplify and find order amidst the chaos. You'll thank yourself later!
____
Did someone forward you this post? We're glad you're here! If you'd like to subscribe to The Daily Meaning to receive these posts directly in your inbox (for free!), just CLICK THIS LINK. It only takes 10 seconds.